/* Inline styles converted to CSS */
.metasync-inline-1 { border-collapse: collapse; }
.metasync-inline-2 { border: 1px solid rgb(193,193,193); padding: 6px; background-color: rgb(233,233,233); text-align: center; }
.metasync-inline-3 { border: 1px solid rgb(193,193,193); padding: 6px; background-color: rgb(233,233,233); text-align: center; }
.metasync-inline-4 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-5 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-6 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-7 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-8 { border-collapse: collapse; }
.metasync-inline-9 { border: 1px solid rgb(193,193,193); padding: 6px; background-color: rgb(233,233,233); text-align: center; }
.metasync-inline-10 { border: 1px solid rgb(193,193,193); padding: 6px; background-color: rgb(233,233,233); text-align: center; }
.metasync-inline-11 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-12 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-13 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-14 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-15 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-16 { border: 1px solid rgb(193,193,193); padding: 6px; }
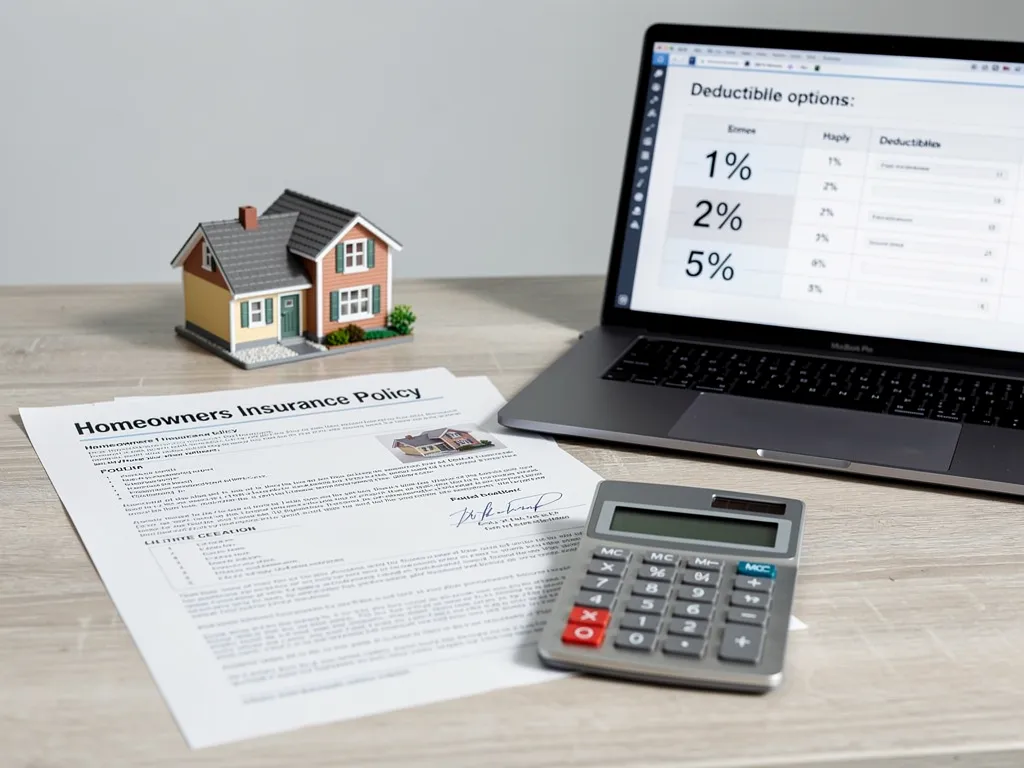
Named storm and hurricane deductibles apply as a percentage of dwelling coverage, typically 1% to 5%, rather than a flat dollar amount, per carrier-specific and state-approved filings. Coastal Insurance Solutions helps coastal homeowners calculate exposure and compare carrier percentages before binding.
- Hurricane deductibles for coastal properties typically range from 1% to 5% of the dwelling's insured value.
- Named storm deductibles apply when specific weather triggers occur, differing from standard homeowners deductibles.
- Coastal homeowners face separate hurricane deductibles that activate during declared hurricane conditions or windstorm events.
- Understanding deductible percentages before storm season reduces claims surprises and protects your coastal property investment.
What's the Difference Between These Deductibles?
Two distinct triggers separate these storm-related costs on a coastal homeowners policy. A hurricane deductible percentage applies only when damage traces back to a formally declared hurricane. A broader trigger picks up storms that never reach hurricane strength.
That broader trigger is the named storm deductible. It applies once the National Weather Service assigns an official name to a tropical storm or tropical depression, not just a full hurricane. For a coastal property, that means a tropical storm sweeping through the region could trigger the same elevated out-of-pocket cost as a Category 2 hurricane making landfall nearby.
Carriers writing coastal policies commonly build one structure or the other into the contract:
Is a storm deductible the same as the standard deductible?
No. A coastal windstorm deductible sits apart from the policy’s everyday deductible and only activates once a qualifying storm event occurs. Homeowners typically pay the standard deductible for routine claims, then face this separate, storm-specific cost when a named or hurricane event causes the damage.
Why does the distinction matter for coastal owners?
A named storm trigger casts a wider net, exposing homeowners to elevated out-of-pocket costs more frequently than a hurricane-only trigger would. Reviewing which structure applies helps coastal property owners anticipate true storm-season exposure before a claim arrives.
How Do Hurricane Deductibles Work?
Many coastal states have approved independent, mandatory hurricane deductibles for homeowners coverage, structured separately from standard storm damage provisions. These separate deductibles apply specifically to storm damage rather than everyday claims. For high-net-worth homeowners across coastal regions, that distinction determines real out-of-pocket exposure during a major storm.
Carriers structure their coastal windstorm deductible around specific triggering circumstances written into each policy. Rather than a flat dollar figure, this deductible often calculates as a percentage of dwelling value. That structure means a higher-value home carries a proportionally higher deductible in dollar terms.
Does the deductible percentage change depending on where the home sits?
Yes. Deductible percentages and their triggers vary by territory, with distinct rules applying across different counties, zip codes, and shoreline zones. A property in one waterfront zip code may face different terms than a similar home just a few miles inland.
What triggers a named storm deductible versus a standard one?
A named storm deductible activates once a storm receives official naming status from meteorological authorities, rather than when high winds alone occur. This trigger mechanism is defined by the carrier itself. Understanding a policy’s exact language matters more than assuming coverage works the same way it did on a prior home.
Coastal Insurance Solutions represents major homeowners’ insurance carriers writing coastal homeowners insurance, helping property owners compare exactly how these structures apply to their specific address.
Why Should Coastal Owners Plan Now?
Waiting until a storm forms in the Atlantic leaves coastal homeowners little room to adjust coverage. A hurricane deductible percentage works differently than a standard flat deductible. The gap between the two can cost thousands of dollars at claim time. Storm damage that triggers this separate deductible often surprises homeowners who assumed their regular deductible applied.
Percentage-based deductibles exist for a reason. Insurers set higher storm deductibles partly to keep annual premiums lower, since homeowners absorb more of the risk themselves. That tradeoff makes sense on paper. It only works in a family’s favor when the numbers are understood ahead of a claim, not during one.
When should a homeowner review their storm deductible?
Coastal storms strike unpredictably, so reviewing deductible structure before a named storm approaches is essential. A named storm deductible and a coastal windstorm deductible can both apply depending on the policy and property location, and each shifts out-of-pocket exposure differently.
Coastal Insurance Solutions, a family-owned independent agency serving coastal homeowners since 2001, helps clients assess these exposures before storm season arrives. Property owners can contact Coastal Insurance Solutions directly to schedule a personalized deductible review.
What triggers a hurricane deductible versus a named storm deductible?
A hurricane deductible activates only when damage results from a formally declared hurricane. A named storm deductible applies once the National Weather Service names a tropical storm or tropical depression, casting a wider net.
Is a hurricane deductible the same as my standard homeowners deductible?
No, a coastal windstorm deductible is separate from the policy’s everyday deductible and only activates when a qualifying storm event causes the damage, rather than for routine claims.
How is the hurricane deductible amount calculated for coastal properties?
Carriers calculate hurricane and named storm deductibles as a percentage of dwelling coverage rather than a flat dollar amount. A higher-value home carries a proportionally higher deductible in dollar terms.
In closing, understanding the distinction between named storm and hurricane deductibles empowers coastal homeowners to make informed decisions about their coverage structure. By evaluating your property’s exposure, risk tolerance, and financial capacity to absorb losses, you align your deductible strategy with your household’s priorities. The right approach protects your assets while maintaining affordability—a balance that requires expertise in coastal risk dynamics. Access to carriers offering genuine flexibility. Your insurance program should reflect your property’s unique profile and your family’s security needs.
In closing, understanding the distinction between named storm and hurricane percentage deductibles is essential for coastal New York homeowners, as these provisions directly shape out-of-pocket exposure when a qualifying event strikes. Reviewing policy language carefully, comparing carrier definitions, and aligning deductible structures with true rebuild costs remain critical steps in sound risk management. As a family-owned agency serving Long Island since 2001, we translate these complex provisions into clear guidance, helping households build resilient, well-structured coverage that safeguards their homes and financial security for years to come.
Ready to Review Your Storm Deductible Exposure?
Understanding how a hurricane or named storm deductible applies to your coastal property shouldn’t wait until a storm is already in the forecast. Coastal Insurance Solutions has helped coastal homeowners evaluate their exposure and compare carrier terms since 2001, and can walk you through exactly how these percentage-based deductibles apply to your specific address.
Contact Coastal Insurance Solutions today to schedule a personalized deductible review:
- Phone: (631) 782-3175
- Email: info@coastalinsurancesolution.com
- Address: 333 Route 25A Suite 150, Rocky Point, NY 11778, US