Secondary Home Insurance Coastal: Vacation Rental Guide

For secondary home insurance coastal, Coastal Insurance Solutions, a family-owned Long Island agency since 2001, adds landlord and vacation rental endorsements to homeowners policies designed for seasonal waterfront properties, covering rental income loss and tenant-related liability. Their Rocky Point, NY team of 50 employees represents major carriers writing homeowners insurance throughout New York for seasonal waterfront rental properties. Contact Coastal Insurance Solutions today to begin a coverage review designed for your property’s rental and flood exposure.

Seasonal waterfront homeowners used as short-term vacation rentals require a landlord or rental-specific endorsement. A standard homeowners policy excludes business use like VRBO or Airbnb bookings. Coastal Insurance Solutions represents major homeowners’ insurance carriers writing homeowners insurance in New York, closing unoccupancy gaps and covering Dwelling (Coverage A) plus rental liability exposure.

Key Takeaways

  • Second home owners require separate insurance policies to protect seasonal waterfront vacation rental properties adequately.
  • Coastal Insurance Solutions represents major homeowners' insurance carriers writing tailored coverage for New York properties.
  • Vacation rental properties face distinct liability concerns requiring specialized endorsements beyond standard homeowners insurance policies.
  • Family-owned since 2001, Coastal Insurance Solutions' 50-person team serves Long Island's secondary property insurance needs.

Why Doesn't Your Homeowners Policy Cover Rentals?
v5 58207 regen 4580084d

Standard homeowners insurance stops protecting a waterfront property the moment money changes hands for guest stays. Insurers classify short-term rental income as a business activity, not personal use. That classification triggers an exclusion clause most owners never notice until a claim gets denied.

The rental income threshold doesn’t matter much either. Even a modest weekend booking schedule can prompt a carrier to exclude the home from standard coverage entirely. Insurers don’t distinguish between a property rented three weekends a year and one booked nearly full-time. Both count as commercial use in their eyes.

Does a small amount of rental income still cause a coverage problem?

Yes. Insurance companies treat any rental income as a business activity, regardless of the amount earned. A property owner collecting occasional guest payments faces the same exclusion risk as one running a full-time rental operation.

Can a mortgage lender require insurance separately from this issue?

Lenders holding a mortgage on the second home often set their own insurance requirements, independent of how the property gets used. According to the National Association of Insurance Commissioners, a lender may require proof of coverage regardless of rental activity.

Owners facing this exposure need more than a standard policy. Coastal Insurance Solutions represents major homeowners insurance carriers writing coverage across New York, giving waterfront property owners access to secondary home insurance coastal options built for rental use, unoccupancy periods, and lender obligations alike.

What Gaps Does a Landlord Endorsement Close?
v5 58207 regen 92601676

A landlord endorsement addresses the coverage gaps left by standard homeowner policies. Secondary home insurance coastal buyers often assume year-round protection exists, but coverage gaps emerge the moment paying guests arrive. Coastal waterfront properties operated as rentals cycle through three distinct uses each year: guest stays, owner vacations, and stretches of vacancy. A single standard policy rarely addresses all three phases at once.

Owner-occupied homeowner insurance simply is not built for tenant activity. Landlord policies, by contrast, are designed around tenant-occupied property. That structural difference is exactly what an endorsement bridges for a seasonal or short-term rental.

What Does a Landlord Endorsement Actually Add?

An endorsement extends vacation home rental insurance to cover the building itself, its attached systems, and its contents under rental use. Dwelling coverage rebuilds the structure with like materials and includes permanent attachments like HVAC and plumbing equipment. Coverage for detached amenities, such as pools, gazebos, and sheds, is usually set as a percentage of dwelling coverage specified in the policy, but can be raised for waterfront features. Personal property coverage typically starts as a percentage of dwelling coverage and adjusts upward for furnished rental contents.

Why Does This Matter for Short-Term Rentals?

Short term rental coastal insurance needs shift constantly between owner use and paying guests. Endorsements keep coverage active across all three occupancy phases, closing the gap standard policies leave open.

How Should Waterfront Owners Handle Flood Risk?
v5 58207 regen 4a5563ba

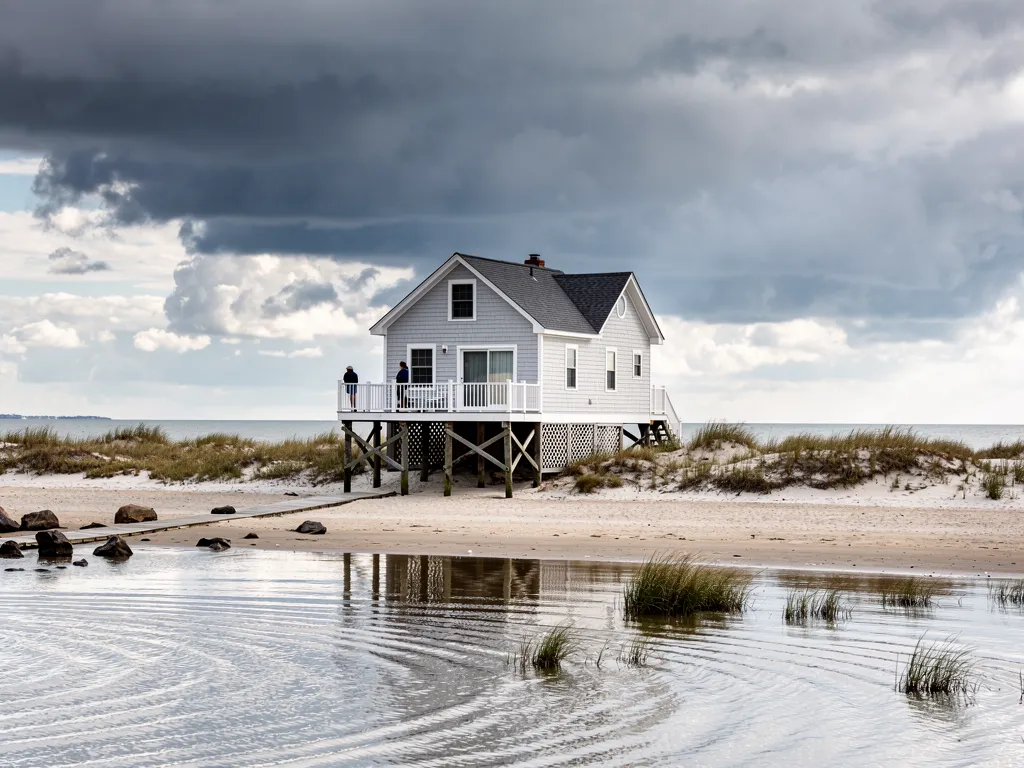
Flood risk requires a dedicated policy separate from standard homeowners insurance. Homeowners insurance and flood insurance remain two separate products entirely. A landlord endorsement attached to a standard policy will not pay for water intrusion from storm surge or rising tides. Waterfront rental properties often carry a separate flood deductible too, distinct from the deductible applied to wind or fire claims under the regular home policy. Owners who assume one deductible covers every peril often discover the gap only after a loss.

Lenders rarely leave this to chance. Properties sitting in high-risk flood zones typically require flood insurance as a mandatory condition of the mortgage, layered on top of standard secondary home insurance coastal coverage.

How much does flood damage actually cost?

The National Flood Insurance Program reports that the average flood claim over the past decade has reached a substantial amount, underscoring the value of dedicated flood coverage. For a property sitting vacant between guest bookings, that exposure grows quietly with every unoccupied week.

What should a flood insurance review include?

  • Confirmation of flood zone designation and lender requirements
  • A deductible comparison between the homeowners and flood policies
  • Coverage adequate for vacation home rental insurance during off-season vacancies
FAQ

Why doesn't a standard homeowners policy cover vacation rental use?

Standard homeowners insurance excludes business activity like VRBO or Airbnb bookings. Insurers classify short-term rental income as a business activity rather than personal use, triggering an exclusion clause many owners discover only after a claim is denied.

Does earning only a small amount of rental income still create a coverage problem?

Yes, insurance companies treat any rental income as a business activity regardless of the amount earned. A property rented occasionally faces the same exclusion risk as one rented nearly full-time.

What does a landlord endorsement fix for waterfront vacation rentals?

A landlord endorsement bridges the gap between owner-occupied coverage and tenant activity, addressing guest stays, owner vacations, and vacancy periods together. Coastal Insurance Solutions closes unoccupancy gaps and covers Dwelling plus rental liability exposure.

Conclusion

In closing, protecting a secondary seasonal waterfront property used for vacation rental requires a specialized insurance approach that standard homeowners policies cannot provide. By securing the appropriate landlord endorsement and flood coverage tailored to your property’s exposure and rental use, you establish a comprehensive shield for your asset, your liability, and your income stream. The complexity of insuring seasonal waterfront rentals demands partnership with advisors who understand coastal risk. The nuances of short-term rental operations—ensuring your investment remains secure regardless of occupancy or weather.

Need assistance now?

Give us a call:
(631) 782-3175

Homeowners Insurance Articles

About the Author

David W. Clausen is the CEO of Coastal Insurance Solutions. With over 20 years' experience and over 1 billion insured, David and Coastal Insurance Solutions are the recognized leaders in high net worth insurance. For the fifth consecutive year, David Clausen has been awarded Top Producer by Insurance Business America. David is a trusted high net worth insurance expert who’s published more than 200 articles. His articles & press releases have generated over 500K pageviews and has been featured on blogs such as Google News, Yahoo Finance, CNBC, Market Watch, Fox, The New York Times, etc. David founded Coastal Insurance Solutions in 2001 after earning a BBA from the State University of New York College at Oswego.

IBA's Top Retail Broker 2023
Digital badge for the 2023 Insurance Agents of the Year Award, featuring intricate design elements that symbolize excellence and achievement in the insurance industry.
IBA's Top Retail Broker 2023
Digital badge for the 2023 Insurance Agents of the Year Award, featuring intricate design elements that symbolize excellence and achievement in the insurance industry.

Helpful Home Insurance Articles