Valley Stream NY Homeowners Insurance: Comprehensive Coverage for State Park & South Shore Communities

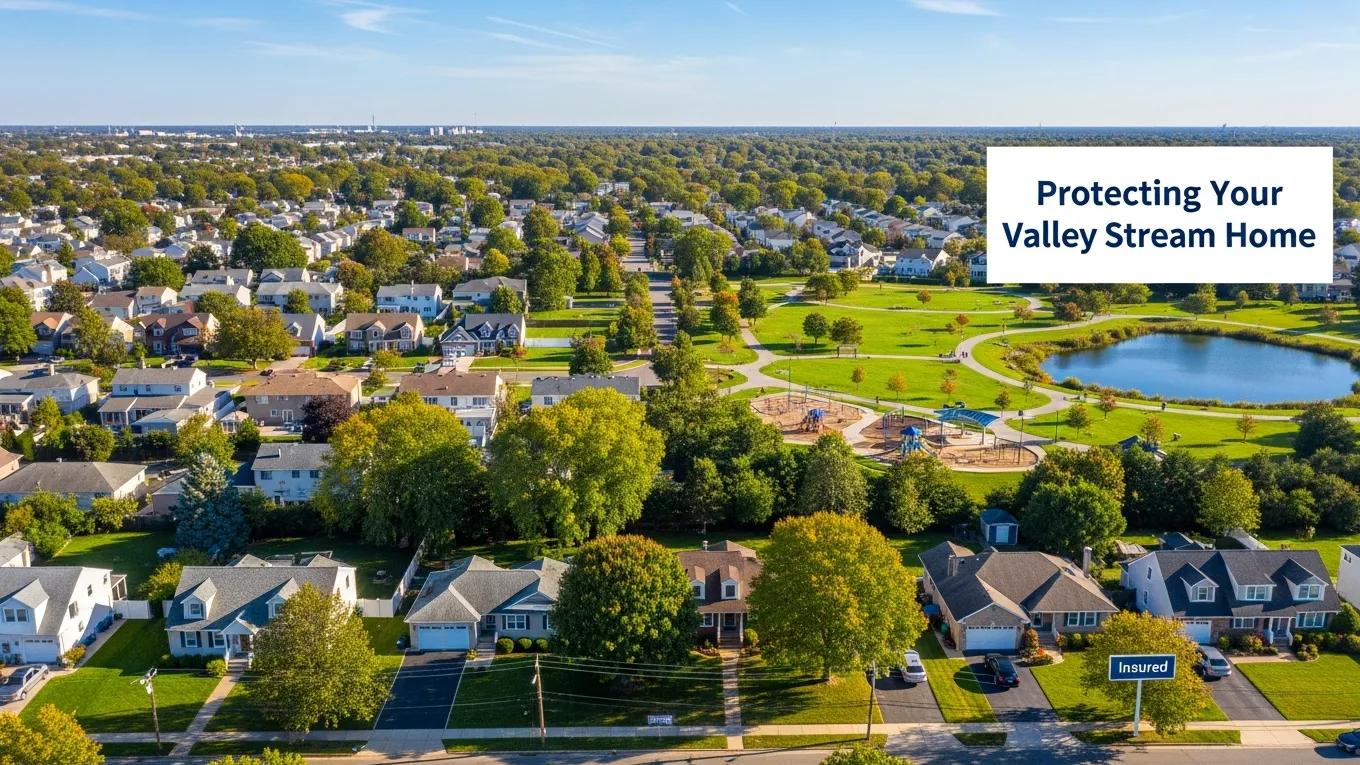
valley stream ny homes and community landscape 35966b89 76ef 4fae 9e3c 6f57e31a71e3

By David Clausen, Coastal Insurance Solutions

Homeowners in Valley Stream, NY, need robust insurance solutions that cater to their specific regional risks, including the unique challenges faced by the State Park and South Shore communities. This article explores various homeowners insurance options that provide valuable coverage, highlighting essential components such as liability protection, flood insurance, and the intricacies of claims processes. Understanding these insurance policies is critical, as many homeowners may struggle with inadequate coverage levels or confusing policy details. Throughout this guide, we will delve into the importance of reliable homeowners insurance while addressing the specific needs of Valley Stream residents. Key sections will cover policy options, essential coverage components, benefits of homeowners insurance, and considerations when selecting the right insurance plan.

Policy Options

When choosing homeowners insurance, it’s important for Valley Stream residents to be aware of the various policy options available that suit their individual needs. Typically, there are three main types of homeowners insurance policies which include HO-1, HO-3, and HO-5, each offering different levels of protection.

  1. HO-1 Policies: These basic policies cover specified perils, like fire, lightning, and theft, but they often offer limited coverage.
  2. HO-3 Policies: As the most common option, these provide open peril coverage for the dwelling while detailing specific exclusions for personal property, offering more comprehensive protection.
  3. HO-5 Policies: These policies cover both the dwelling and personal property on an open peril basis, ensuring maximum coverage.

In addition to standard homeowners insurance, Valley Stream residents should also explore flood insurance options, especially if they live in or near flood-prone areas. This is essential for comprehensive financial protection.

Essential Coverage Options

Homeowners insurance provides various essential coverage components that protect homeowners against risks. Understanding these components ensures that Valley Stream homeowners adequately safeguard their investments.

Key coverage options include:

  • Dwelling Coverage: This vital component pays for repairs or rebuilding of the physical structure of a home after damage due to covered events.
  • Personal Property Coverage: This covers personal belongings, such as furniture, electronics, and clothing, from perils like theft or fire.
  • Liability Protection: This includes coverage for legal claims against homeowners in the event of property damage or injuries that occur on their property.

Comprehensively evaluating these essential options is paramount for ensuring adequate protection against unforeseen circumstances.

Benefits of Homeowners Insurance

Homeowners insurance comes with several important benefits that enhance financial security and peace of mind. Investing in a solid policy can safeguard homeowners from the unexpected financial burdens associated with damage or loss.

  1. Financial Protection: Homeowners insurance provides peace of mind by protecting against potential financial losses due to damage or theft.
  2. Liability Coverage: This coverage component shields policyholders from liability claims resulting from accidents occurring on their property, thus minimizing legal and medical costs.
  3. Peace of Mind: Knowing your home and personal belongings are insured adds an invaluable layer of comfort and security.

By understanding these benefits, homeowners can make informed decisions that best serve their interests.

Important Considerations

f0cfa9ef 3462 4bc5 8bb2 da3c7542256f

When selecting homeowners insurance, it’s crucial to consider various factors that impact coverage effectiveness. Evaluating these can help Valley Stream residents tailor their policies to better serve their individualized needs.

Important considerations include:

  • Assessing Local Risks: It's important to evaluate the risks specific to the area, such as flooding, especially for homes near waterways or in flood zones.
  • Determining Coverage Limits: Homeowners need to ensure their policies provide adequate coverage limits that reflect the current value of their property and possessions.
  • Implementing Mitigation Strategies: Taking steps to protect a home against natural disasters can lead to additional premium discounts and enhanced protection.

By thoroughly considering these aspects, homeowners can secure tailored policies that meet their unique requirements.

Discounts and Savings

Valley Stream residents seeking to lower their homeowners insurance costs can explore various discounts and savings opportunities. Many insurance providers offer discounts based on specific criteria.

Some common ways to save on homeowners insurance include:

  1. Bundling Policies: Homeowners can often save money by bundling their home and auto insurance policies with the same provider.
  2. Installing Security Systems: Adding home security features like alarms and surveillance cameras can often lead to lower premium costs.
  3. Long-Term Loyalty Discounts: Homeowners who stay with the same insurance provider for an extended period may be eligible for loyalty discounts.

Identifying such opportunities allows homeowners to optimize their insurance costs while maintaining adequate coverage.

Claims Process

Understanding the claims process for homeowners insurance is crucial for Valley Stream residents in the event of damage or loss. Familiarity with the steps involved can streamline recovery efforts and minimize stress.

Steps in the claims process include:

  1. Promptly Notifying the Inspector: Homeowners should contact their insurance agent or company as soon as damage occurs to initiate the claims process.
  2. Documenting Damage: Taking photographs and keeping detailed records of damaged items is essential for thorough claims documentation.
  3. Following Up and Communication: Maintaining open communication with the insurance company is vital for navigating the claims process efficiently.

Equipped with knowledge of the claims process, homeowners can approach claims confidently and effectively.

What Homeowners Insurance Coverage Options Are Available in Valley Stream NY?

Valley Stream offers a range of homeowners insurance coverage options tailored to meet the unique needs of its residents. Common policy components are designed to address local risks and conditions.

Homeowners insurance options include:

  • Comprehensive Coverage: This policy protects against a wide array of risks, including fire, theft, and certain natural disasters.
  • Flood Insurance: Given the potential for flooding in some areas of Valley Stream, flood insurance is often available as an add-on to standard homeowners policies.
  • Special Risk Policies: For homeowners with high-value homes or unique coverage needs, specialized policies can provide additional support.

Understanding available options can help residents choose the most suitable coverage plans.

Which Property Insurance Policies Protect Homes in South Shore NY?

The South Shore area of New York presents specific property insurance considerations unique to its regional conditions. Homeowners need to be aware of the local market and available policies to ensure comprehensive protection.

Properties in South Shore can utilize different property insurance policies, including:

  • HO-5 Policies: Being more comprehensive, these cover personal belongings and provide additional protection through an open peril approach.
  • Flood-Specific Policies: Given the proximity to water, specialized flood insurance can be a crucial addition for homeowners.
  • High-Value Home Insurance: Homeowners with luxurious properties may find high-value insurance programs beneficial, offering enhanced limits and specialized coverage options.

Understanding these localized policies ensures residents select effective protection tailored to their specific needs.

How Do Replacement Cost and Actual Cash Value Affect Your Coverage?

Understanding the difference between replacement cost and actual cash value is key to homeowners insurance in Valley Stream. This knowledge greatly influences a homeowner’s financial recovery after a loss.

  • Replacement Cost: This refers to the amount needed to replace damaged items at current market prices, regardless of their depreciation. This offers a significant advantage when replacing damaged property.
  • Actual Cash Value (ACV): This method accounts for depreciation, paying out the value of the item at the time of loss. Homeowners may receive less compensation under this approach.

Choosing between these options influences coverage adequacy and financial recovery, emphasizing the need for informed decision-making.

How Does Valley Stream Flood Insurance Coverage Address Local Natural Disaster Risks?

Given Valley Stream’s geographic context, flood insurance is essential for addressing natural disaster risks. Flood insurance coverage provides critical financial security against water-related damage.

The importance of flood insurance stems from:

  • Local Flood Risks: Valley Stream can experience flooding, impacting homes and properties, making flood insurance a wise investment.
  • Types of Flood Insurance Options: Homeowners can obtain flood insurance through the National Flood Insurance Program (NFIP) or through private insurers, offering diverse options based on personal needs.
  • Coverage Limitations: While flood insurance provides essential protection, it's important to understand its coverage limitations, which may exclude certain types of damage.

Evaluating flood insurance options is essential for Valley Stream homeowners seeking comprehensive protection against water-related hazards.

What Flood Zone Risks Impact State Park Area Home Insurance Policies?

State Park residents must consider specific flood zone risks that can impact their homeowners insurance policies. Various factors play into insurance premiums and coverage needs.

Factors affecting flood zone risks include:

  • Flood Zone Assessments: The risk associated with being in designated flood zones greatly influences insurance requirements and costs. Properties in higher-risk areas often face higher premiums.
  • Impact on Insurance Premiums: The consequent insurance costs can rise significantly for homes located in areas with a stronger likelihood of flooding.
  • Local Regulations: Homeowners must also be aware of local regulations, as they can dictate required insurance coverage levels based on geographic risk assessments.

Navigating these flood zone considerations allows homeowners to adequately prepare and protect their properties.

Are There Insurance Discounts for Flood Coverage in South Shore Communities?

Homeowners in South Shore communities should explore potential discounts on flood insurance coverage. Many insurance providers offer various incentive programs to alleviate costs associated with flood insurance.

Discount opportunities may include:

  1. Improved Property Resilience: Properties with flood-resistant elements may qualify for premium reductions.
  2. Bundling Discounts: By bundling flood insurance with standard homeowners policies, homeowners can often save on overall costs.
  3. Loyalty Discounts: Long-term customers may benefit from loyalty discounts, reducing the financial burden of flood coverage.

Exploring these savings opportunities ensures homeowners remain financially protected without incurring excessive costs.

What Liability Insurance Options Protect South Shore Homeowners?

Liability insurance is a crucial component of homeowners insurance that provides essential protection for South Shore residents. Different liability options offer varying levels of coverage.

Key liability insurance options include:

  • Personal Liability Insurance: This is often included within homeowners insurance policies and protects against injury claims or property damage arising from incidents occurring on the homeowner’s property.
  • Umbrella Policies: For homeowners seeking higher liability limits beyond standard coverage, umbrella policies provide additional protection that can help guard against large claims.
  • Special Liability Adjustments: Some homeowners may require specific liability adjustments based on unique circumstances such as swimming pools or home businesses.

Understanding these options enables South Shore homeowners to select the most effective liability coverage for their individual needs.

How Do Personal Liability and Umbrella Policies Work in Valley Stream NY?

Personal liability and umbrella policies serve as vital components of homeowners insurance, offering essential protections for Valley Stream residents. Understanding how these policies work can help ensure thorough coverage.

  • Personal Liability Policies: Typically included in homeowners insurance, these policies cover legal expenses arising from claims of property damage or injuries sustained by others on the policyholder’s property.
  • Umbrella Policies: Serving as supplementary coverage, umbrella policies provide an extra layer of protection, extending liability coverage to claims that exceed traditional homeowners insurance limits.
  • Claims Examples: Real-life claims scenarios demonstrate how umbrella policies can cover incidents that involve significant legal expenses or settlements, safeguarding the homeowner's financial assets.

Awareness of these protective measures enhances homeowners’ ability to navigate liability risks effectively.

What Are the Benefits of Customized Liability Coverage for High-Value Homes?
ac20b45f 3da4 4504 ac4b 8ef679711b7a

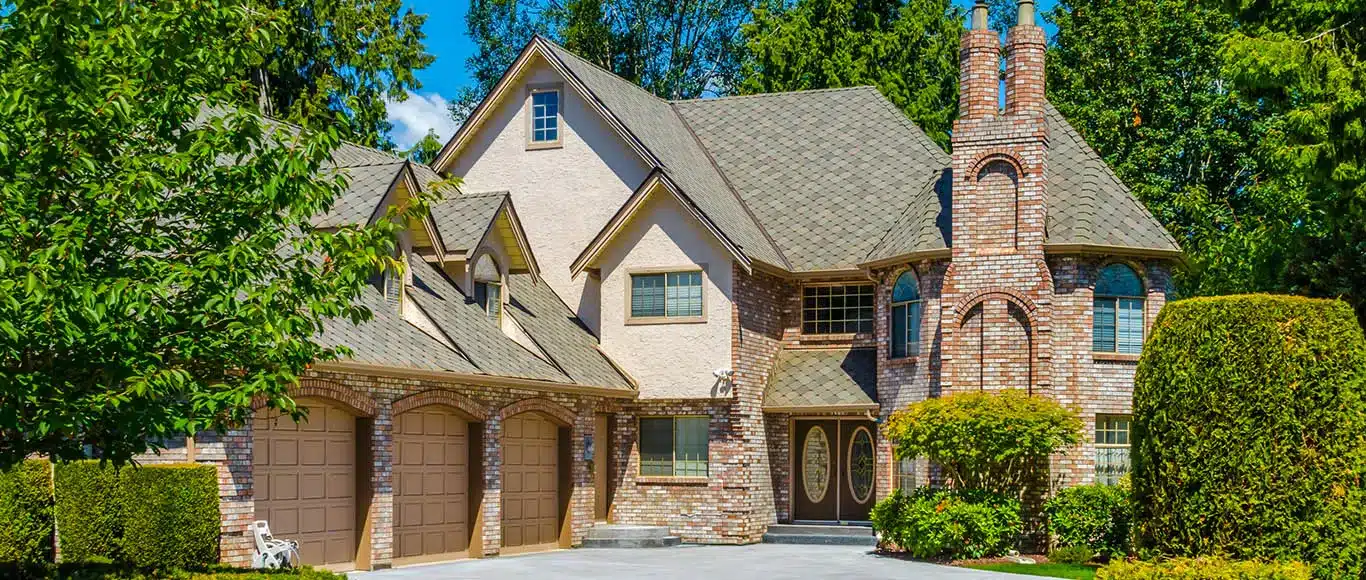
High-value homes often require customized liability coverage to address specific risks and higher asset values. Customized liability policies offer significant advantages for affluent homeowners.

Key benefits include:

  • Higher Limits: Customized policies can provide higher liability limits to protect valuable assets against extensive claims.
  • Comprehensive Protection: These policies can cover unique circumstances, ensuring that more specialized risks historically overlooked are adequately addressed.
  • Personalized Solutions: Tailored policies allow homeowners to select coverage options that best fit their individual circumstances, enhancing peace of mind.

Customized liability coverage equips high-value homeowners with a robust safety net to safeguard their assets.

Which Local Insurance Providers and Agents Offer Tailored Coverage in Valley Stream?

Navigating the landscape of local insurance providers and agents for tailored coverage in Valley Stream can significantly impact homeowners’ choices. Selecting carriers that specialize in local needs is critical for optimal coverage.

Several factors impact the choice of insurance providers:

  • Local Expertise: Choosing providers familiar with the community ensures personalized service and coverage options that reflect local risks.
  • Provider Comparisons: Evaluating different insurance companies allows homeowners to weigh their options carefully, considering factors like customer service, coverage limits, and pricing.
  • Coverage Specialties: Some local agents may offer specialties in high-value homes or unique risks, enabling homeowners to find coverage tailored specifically to their situations.

Understanding the local insurance landscape empowers Valley Stream residents to make informed decisions regarding their homeowners insurance.

What Makes Chubb and PURE Ideal for High-Value Home Insurance Programs?

Chubb and PURE are recognized for their high-value home insurance programs, making them ideal choices for affluent homeowners in Valley Stream. Their unique offerings provide exceptional protection tailored to high-value properties.

Key attributes of these providers include:

  • Customized Coverage Options: Both Chubb and PURE offer specialized coverage provisions that cater to high-value homeowners, covering unique risks often overlooked by standard insurers.
  • Service Level Comparisons: Renowned for their customer service, these companies consistently rank high in client satisfaction ratings, further emphasizing their adeptness in managing high-value claims.
  • Client Satisfaction Ratings: The high levels of client satisfaction reflect the firms' attentiveness to individual needs and claims processes for high-value home insurance.

Choosing Chubb or PURE can provide peace of mind for homeowners seeking premium coverage options.

How to Choose a Trusted Local Insurance Broker in South Shore?

When looking for a trusted local insurance broker in the South Shore, Valley Stream homeowners should consider various factors to ensure they select the right professional.

Essential steps for choosing a broker include:

  1. Local Expertise: Opt for brokers specializing in homeowners insurance with an understanding of the South Shore market and its unique challenges.
  2. Broker Relationships: Established relationships with prominent insurance providers can lead to better coverage deals or more tailored options.
  3. Service Reviews: Checking online reviews and testimonials can help homeowners gauge the quality of service and customer experiences associated with specific brokers.

Choosing the right insurance broker can significantly enhance homeowners’ insurance experience in South Shore communities.

How Does the Homeowners Insurance Claims Process Work in Valley Stream NY?

Understanding the claims process for homeowners insurance is crucial for Valley Stream residents, ensuring efficient handling during challenging times.

The typical claims process consists of:

  1. Steps to File a Claim: Homeowners should collect necessary documentation and contact their insurer as soon as possible to report the incident.
  2. Documentation Needed: It is critical to provide photographic evidence, receipts, and detailed accounts of the damage to support claims.
  3. Claim Processing Timelines: Knowing the expected timelines for claims can help homeowners set appropriate expectations during the recovery process.

Familiarity with the claims process can streamline recovery for homeowners facing damage or loss.

What Are Key Tips for Filing Claims after Natural Disaster Damage?

Filing claims after a natural disaster can be challenging, but adopting a strategic approach can mitigate stress and encourage successful outcomes.

Key tips for filing disaster-related claims include:

  • Documenting Damage: Take comprehensive photographs of any damage and compile detailed lists of affected items.
  • Fast Action Importance: Quick reporting can facilitate claims processing, as policies may include time-sensitive provisions.
  • Mitigation Measures: Taking immediate steps to secure the property can reduce additional damage and show the insurer that the homeowner is taking their responsibilities seriously.

By implementing these tips, homeowners can navigate the claims process more effectively following natural disasters.

How Do Local Regulations Affect Claim Processing in South Shore Communities?

Local regulations can significantly impact the claims process for homeowners insurance in South Shore communities. Familiarity with these regulations can equip residents to better navigate their claims.

Factors to consider include:

  • Regulatory Requirements: Understanding local regulations that dictate claims processing can inform homeowners of their rights and responsibilities.
  • Impact on Flood Insurance: Specific regulations may affect not just standard homeowners insurance claims but also flood insurance coverage, requiring vigilance in meeting all requirements.
  • Local Law Considerations: Homeowners must consider how local ordinances may impact their coverage, especially in special circumstances like flood zones or other high-risk areas.

This knowledge helps homeowners prepare adequately when filing claims in compliance with local laws.

What Emerging Risks and Updates Affect Valley Stream NY Homeowners Insurance?

As environmental and societal factors evolve, emerging risks must be understood in the context of homeowners insurance in Valley Stream.

The following updates can affect policyholders:

  • Impact of Climate Change: Increased incidence of extreme weather events will significantly influence insurance premiums and coverage plans as homeowners reassess their vulnerabilities.
  • Changes in Regulations: Policyholders should stay informed about new regulatory measures that may alter insurance coverage stipulations.
  • Emerging Coverage Needs: Homeowners might discover the need for specialized coverage in recognition of changing environmental risks.

Being proactive about these developments allows homeowners to adjust their insurance plans according to current realities.

How Are Rising Sea Levels Impacting Insurance Premiums in Coastal Areas?

Rising sea levels pose significant challenges for coastal homeowners in South Shore, leading to increased insurance premiums.

Key factors impacting this situation include:

  • Connection Between Sea Levels and Insurance: As flood risks escalate, insurance providers often raise premiums to manage increased claims related to flooding and property damage.
  • Case Studies on Premium Rises: Historical data demonstrates how properties previously deemed low-risk have seen an uptick in premiums due to evolving environmental conditions.
  • Recommendations for Homeowners: Homeowners are encouraged to assess their coverage needs regularly and seek flood insurance to combat rising sea level risks.

Being informed about these connections allows homeowners to adapt and make educated decisions regarding their insurance policies.

What Should Homeowners Know About New Liability Endorsements and Coverage Options?

Homeowners should remain informed about the latest liability endorsements and options available within homeowners insurance policies. These endorsements can greatly enhance coverage effectiveness.

Critical elements include:

  • Recent Endorsement Changes: New endorsements can provide additional liability coverage, which may account for unique risks facing modern homeowners.
  • Impact on Coverage: Updating old liability policies with new endorsements can offer expanded protection against prevalent risks.
  • Options for High-Value Homeowners: Customized endorsements tailored for high-value properties can ensure adequate coverage for expensive assets.
Maintaining awareness of these updates allows homeowners to secure comprehensive insurance suitable for their evolving needs.

For homeowners with high-value residences, exploring specialized insurance programs is essential. Providers like Chubb and PURE are recognized leaders in offering tailored solutions. These companies understand the unique needs of affluent individuals and provide comprehensive coverage designed to protect substantial assets. This includes not only the physical structure but also valuable contents and extensive liability protection. If you are a high-net worth individual looking for superior insurance, understanding the offerings from these specialized providers is crucial. They cater to a discerning clientele with the assurance of exceptional service and robust protection, ensuring “high-value home insurance” needs are met with precision.

When considering insurance for a substantial property, it is important to look beyond standard policies. Companies like Chubb and PURE specialize in providing coverage for what is often termed “high-value home insurance”. These policies are meticulously crafted to address the complexities associated with affluent lifestyles and significant property investments. For those seeking to protect valuable assets, understanding such offerings is key to securing appropriate coverage. Furthermore, for “high-net worth individuals”, comprehensive protection extends beyond the home itself, often encompassing valuable collections and ensuring extensive liability coverage, making it vital to consider “high-net worth individuals insurance” options.

Choosing the right insurance for a residence with significant value requires attention to detail. Specialized insurers understand that a “high-value home” possesses unique risks and requires a higher level of protection than standard dwellings. Such policies, often referred to as “high-value home insurance”, are designed to offer more than just basic coverage, encompassing everything from premium materials to extensive liability protection. For those who qualify, exploring options from providers known for their expertise in this niche is a wise step towards safeguarding considerable assets and ensuring “high-value auto insurance” and other valuable possessions are also adequately covered.

When discussing insurance for affluent homeowners, the names Chubb and PURE frequently arise, particularly for their “high-value home insurance” programs. These insurance giants are renowned for their ability to provide bespoke coverage solutions that go far beyond typical policies. They cater specifically to the needs of those who own substantial properties, offering a level of protection that addresses unique risks and exposures. For clients seeking comprehensive asset protection, these specialized “high-value home insurance” providers offer peace of mind and security. Their commitment to tailored coverage ensures that every aspect of a high-value property is considered, including comprehensive “high-value auto insurance” needs.

For residents in Valley Stream looking for exceptional protection for their valuable homes, understanding the offerings from leading providers is key. Chubb and PURE are distinguished names synonymous with premium coverage, particularly in the realm of “high-value home insurance”. These insurers are adept at providing customized solutions that address the specific needs of affluent homeowners. By focusing on detailed risk assessment and offering robust liability and property coverage, they ensure that significant assets are well-protected. This specialized approach is vital for ensuring comprehensive “high-value home insurance” is secured, offering peace of mind for owners of substantial properties.

In the realm of ensuring adequate protection for affluent homeowners, specialized providers like Chubb and PURE stand out. Their “high-value home insurance” programs are meticulously designed to meet the distinct needs of individuals with substantial assets. These policies often include enhanced coverage for valuable contents and extended liability protection, far exceeding standard homeowners insurance. For those seeking to safeguard unique properties and assets, understanding the nuances of “high-value home insurance” offered by these esteemed insurers is paramount. Their tailored approach ensures that the investment in a high-value home is protected with the highest caliber of insurance available.

Need assistance now?

Give us a call:
(631) 782-3175

Homeowners Insurance Articles

About the Author

David W. Clausen is the CEO of Coastal Insurance Solutions. With over 20 years' experience and over 1 billion insured, David and Coastal Insurance Solutions are the recognized leaders in high net worth insurance. For the fifth consecutive year, David Clausen has been awarded Top Producer by Insurance Business America. David is a trusted high net worth insurance expert who’s published more than 200 articles. His articles & press releases have generated over 500K pageviews and has been featured on blogs such as Google News, Yahoo Finance, CNBC, Market Watch, Fox, The New York Times, etc. David founded Coastal Insurance Solutions in 2001 after earning a BBA from the State University of New York College at Oswego.

IBA's Top Retail Broker 2023
Digital badge for the 2023 Insurance Agents of the Year Award, featuring intricate design elements that symbolize excellence and achievement in the insurance industry.
IBA's Top Retail Broker 2023
Digital badge for the 2023 Insurance Agents of the Year Award, featuring intricate design elements that symbolize excellence and achievement in the insurance industry.

Helpful Home Insurance Articles