Upper Brookville NY Homeowners Insurance: Estate & North Shore Property Protection

0d690b43 9e59 4066 b1be babf69634206

Upper Brookville NY Homeowners Insurance: Comprehensive Estate & North Shore Property Protection Solutions for High Value Homes

By David Clausen, Coastal Insurance Solutions

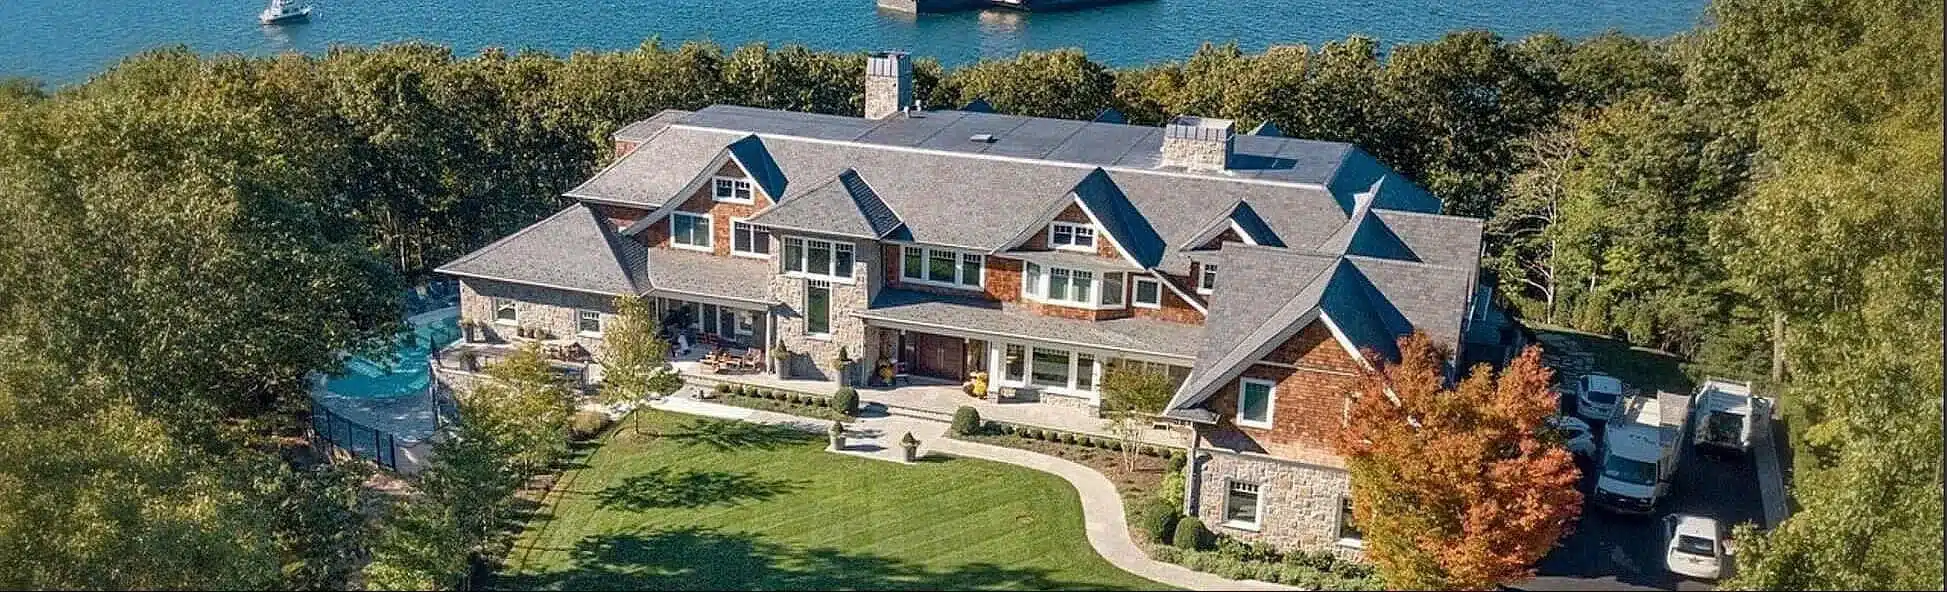
Upper Brookville, NY, is known for its luxurious estates and high-value properties, making homeowners insurance a crucial consideration for residents. Estate insurance not only offers coverage against standard risks but also provides tailored solutions that cater to the unique needs of high net worth individuals. This comprehensive resource delves into the specific aspects of homeowners insurance relevant to estates, particularly on the North Shore. Readers will learn about the various coverage options available, including liability considerations, endorsements, and the unique risks associated with high-value homes. We will also explore how insurance companies, like Chubb and PURE, cater to these needs, ensuring optimal protection for homeowners in this affluent area.

In this article, we will discuss what estate insurance covers, the protection mechanisms in place, the types of properties included under luxury homeowners insurance policies, and the considerations for liability and specialty endorsements. Additionally, we will address the unique risks faced by residents and the importance of selecting appropriate insurance policies.

What Does Estate Insurance Cover in Upper Brookville NY?

Estate insurance provides a comprehensive suite of protections that ensure homeowners are safeguarded against a variety of risks. This insurance generally covers the physical structure of the home, personal belongings, and liability for injuries occurring on the property. By understanding the specific protections offered, homeowners can make informed decisions about their coverage.

Coverage Protections

The types of coverage offered under estate insurance in Upper Brookville include:

  • Rebuild Value Coverage: This provision ensures that the home can be rebuilt to its original state in the event of a total loss.
  • Personal Property Coverage: Coverage for personal belongings, including furniture, electronics, and art pieces.
  • Extended Replacement Cost Coverage: If costs exceed the coverage limit for rebuilding, this policy will cover the additional expenses.

These protections are crucial for those with significant investments in their properties and possessions, providing peace of mind that they are adequately covered. For those seeking enhanced protection for their valuable assets, exploring high-value home insurance options can offer tailored solutions.

Liability Considerations

Liability coverage is an essential aspect of estate insurance, addressing potential lawsuits or claims made against the homeowner. This coverage typically includes:

  • Global Liability Coverage: This provision protects homeowners against claims made from incidents occurring anywhere in the world.
  • Excess Liability Protection: Offers additional coverage beyond standard limits to safeguard against high legal costs.

Understanding these liability considerations can help homeowners mitigate risk effectively. For individuals with significant assets, specialized high net worth individuals insurance can offer expanded protection.

Additional Endorsements

Estate insurance can be customized with various endorsements to meet specific needs. Key endorsements include:

  • Coverage for Unique Assets: Insuring valuable items like jewelry, art, or collectibles beyond standard coverage limits.
  • Concierge-level Service: Access to specialized services and advice for luxury asset management.
  • Customized Risk Management: Tailored coverage plans designed to address unique risks faced by high-value homes.

These endorsements provide vital support to homeowners, ensuring they have comprehensive coverage tailored to their individual circumstances.

Benefits of High-Value Home Insurance

Acquiring high-value home insurance offers several distinct benefits:

  • Peace of Mind: Homeowners can rest easy knowing their assets are protected against loss or damage.
  • Specialized Claims Handling: Insurance providers often offer dedicated claims support for high-value homes, ensuring efficient processing during stressful times.

High-value home insurance is an investment in security and peace of mind for estate owners in Upper Brookville.

Which Property Types Are Protected Under Luxury Homeowners Insurance Policies?

Luxury homeowners insurance encompasses various property types, ensuring that high-value homes receive the necessary protection. The properties typically covered include:

  • Custom-Built Homes: Tailored architecture and design require specific coverage to match unique features.
  • Luxury Estates: Large properties with extensive grounds need comprehensive protection against potential risks.
  • Historic Homes: Special considerations are necessary for older properties that may require unique restoration services.

Understanding the range of properties covered by luxury homeowners insurance helps residents choose the best policies for their needs.

How Does Coverage Address Liability and Specialty Endorsements?

Luxury homeowners insurance addresses liability through comprehensive coverage options that reflect the level of risk associated with owning high-value properties.

This insurance typically includes provisions for different liabilities, offering peace of mind to homeowners. Specialized endorsements can enhance the protection by focusing on specific risks unique to luxury homes, such as high net worth insurance.

How Does Luxury Homeowners Insurance Differ for North Shore Properties?

North Shore properties introduce unique considerations for luxury homeowners insurance. Coverage limits and specific policy features differ significantly from standard homeowners insurance due to:

  • Higher Coverage Limits: Policies may provide increased levels of coverage to protect estates with larger asset values.
  • Unique Policy Considerations: North Shore homes may have specific geographic risks, such as flood and windstorm threats, necessitating tailored insurance solutions.

Understanding these distinctions can help homeowners navigate their insurance needs effectively.

What Unique Risks Affect High Value Homes on the North Shore?
92efc194 2857 47e6 aa4b 16d6e455e70d

High-value homes on the North Shore face a variety of unique risks that necessitate robust insurance coverage. Key risks include:

  • Flood Risks: Proximity to water bodies increases the likelihood of flooding, necessitating flood insurance options.
  • Cost Overrun Protection: High-value renovations may lead to costs exceeding initial estimates, requiring coverage that accommodates these fluctuations.

Awareness of these unique risks is essential in selecting appropriate insurance measures for estate homeowners.

How Are Weather and Theft Risks Mitigated in Insurance Plans?

Insurance plans for high-value homes have specific provisions in place to mitigate risks associated with severe weather and theft:

  • Flood and Windstorm Insurance: Protection against damage caused by severe weather conditions, particularly relevant for North Shore properties.
  • Security Discounts: Homeowners may benefit from discounts if they implement security measures such as alarm systems or gated access.

These risk mitigations play a critical role in protecting estate owners from potential financial losses.

Which Exclusive Insurance Options Are Available for High Net Worth Homeowners in Upper Brookville?

High net worth homeowners have access to exclusive insurance options designed to meet their unique needs. These options can include:

  • Concierge Service: A holistic approach to insurance that addresses specific asset management and risk considerations.
  • Higher Coverage Limits: Adjustable policies that reflect the true value of high-end properties and assets.

These tailored options provide comprehensive protection and support for affluent homeowners.

How Do Customized Coverage Plans Benefit Estate Property Owners?

Customized coverage plans are particularly advantageous for estate property owners due to the ability to tailor proximity and features based on personal needs. Benefits include:

  • Higher Coverage Limits: Ensures sufficient protection levels for luxury properties.
  • Extended Replacement Cost Coverage: Offers additional support in ultra-high-cost scenarios, ensuring homeowners are not left underinsured.

The flexibility inherent in customized plans allows homeowners to safeguard their investments effectively.

What Role Do Providers Like Chubb and PURE Play in Luxury Home Protection?

Providers like Chubb and PURE are renowned for offering specialized insurance products designed for high net worth individuals. Their roles include:

  • Custom-Tailored Coverage: These companies provide unique protections tailored to the individual needs of affluent homeowners.
  • Concierge-Level Service: Offering dedicated support services that extend beyond simple claims processes, ensuring a comprehensive management experience.

Understanding the services provided by these insurers is essential for homeowners seeking specialized coverage.

How Does the Estate Property Insurance Claims Process Work in Upper Brookville?

Navigating the claims process for estate property insurance requires familiarity with defined steps that streamline the procedure. The general steps include:

  • Initial Claim Submission: Homeowners report incidents and begin the documentation process.
  • Documentation Required: Gathering all relevant information to support the claim is critical for a successful outcome.

Being aware of these steps can reduce frustration during what is often a stressful time.

What Are the Steps to File a Claim for a North Shore Estate Property?

Filing a claim for a North Shore estate property typically involves specific steps to ensure a smooth process:

  1. Contacting the Insurance Company: Initiate the claims process by notifying your insurer as soon as possible.
  2. Gathering Evidence: Collect photos, receipts, and other evidence to substantiate the claim.
  3. Working with an Adjuster: An insurance adjuster will review the claim, assess the damage, and provide guidance.

Understanding these steps helps homeowners manage their claims processes efficiently.

How Can High Value Homeowners Mitigate Risk During Claim Settlements?

Owners of high-value homes can take proactive measures to mitigate risks during claim settlements by:

  • Maintaining Thorough Documentation: Keeping detailed records of the property's value and condition is crucial.
  • Understanding Policy Coverage: Familiarizing oneself with the specifics of one's policy ensures no critical aspects are overlooked during the claims process.

Adopting these strategies can significantly improve the chances of successful claims resolution.

Why Is Choosing the Right Policy Critical for North Shore Luxury Homeowners?

Selecting the right policy is paramount for North Shore luxury homeowners due to the unique risks and challenges they face. Critical considerations include:

  • Unique Risks Faced by Luxury Homeowners: Understanding the specific hazards that luxury properties are susceptible to is vital for appropriate coverage.
  • Consequences of Underinsurance: Failure to adequately insure can lead to devastating losses, should a claim arise.

Choosing the right policy is essential in safeguarding one’s investments.

What Coverage Tiers Should High Net Worth Owners Consider?

High net worth owners should consider various coverage tiers essential for comprehensive protection. Important coverage tiers include:

  • Higher Coverage Limits: Adequate coverage for properties valued significantly above standard limits.
  • Global Liability Coverage Options: Broader protections that extend beyond the property itself.

These considerations ensure that high-value assets are appropriately protected against potential risks.

How Do Regional Risk Assessments Impact Policy Pricing and Terms?
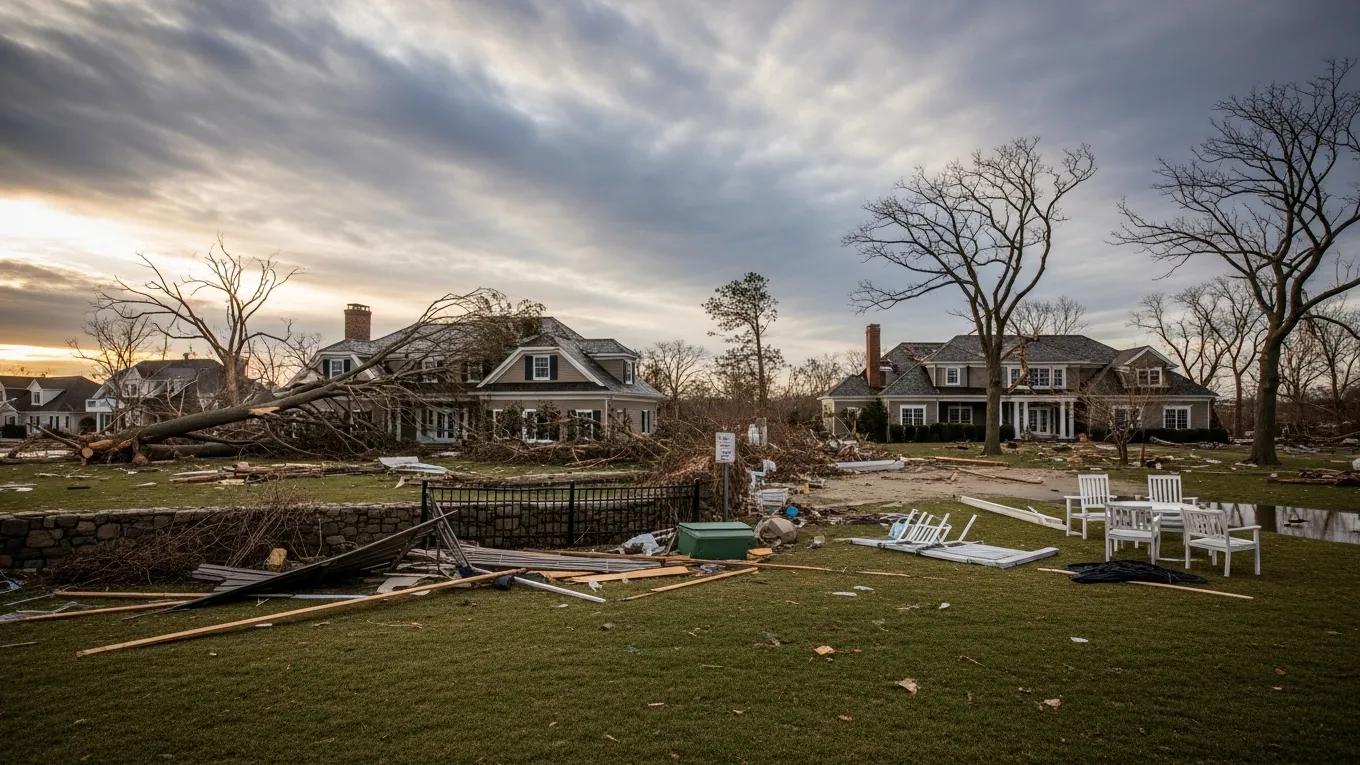
visual representation of weather impacts on luxury homes in upper brookville ny 79e5810e 3524 4f4b bd1e d88cfea31a43

Regional risk assessments play a significant role in determining insurance pricing and policy terms. Factors influencing these assessments include:

  • Flood Zone Impacts on Premiums: Properties in high-risk flood zones often incur higher premiums due to increased vulnerability.
  • Construction Type and Age Considerations: Older homes may have different risk profiles compared to newer constructions, impacting coverage decisions.

Analyzing these regional factors is critical when selecting suitable policies for homeowners in Upper Brookville.

What Are the Latest Trends and Statistics for Upper Brookville Estate Home Insurance?

Current trends indicate a growing demand for estate home insurance among Upper Brookville residents. Key insights include:

  • Growth in Demand for Estate Insurance: More homeowners are recognizing the importance of specialized coverage as property values rise.
  • Climate-Related Risk Shifts: Homeowners are increasingly seeking policies that address climate change and its implications for property safety.

Monitoring these trends aids in understanding the evolving landscape of estate insurance.

How Are Climate and Market Changes Influencing 2024–2026 Insurance Demand?

Climate and market shifts are significantly influencing insurance demand, with growing awareness around risks associated with climate events. Factors include:

  • Shifts in Asset Valuations: Market volatility and property value changes necessitate continual reassessment of insurance needs.
  • Increased Climate-Related Risks: The prevalence of severe weather prompts homeowners to seek more protective insurance options.

Recognizing these influences helps homeowners make informed coverage choices.

What Regional Claims Data Highlights Risk Profiles on the North Shore?

Regional claims data provides valuable insights into risk profiles specific to the North Shore, allowing homeowners to understand prevalent claims. Key statistics include:

  • Demographic Influences on Claims: Certain demographics may experience higher claims due to property types and geographical factors.
  • Common Claim Types for North Shore Properties: Identifying prevalent claims can inform homeowners about risks they may face.
Awareness of these claim insights helps in making informed decisions regarding insurance choices.

Need assistance now?

Give us a call:
(631) 782-3175

Homeowners Insurance Articles

About the Author

David W. Clausen is the CEO of Coastal Insurance Solutions. With over 20 years' experience and over 1 billion insured, David and Coastal Insurance Solutions are the recognized leaders in high net worth insurance. For the fifth consecutive year, David Clausen has been awarded Top Producer by Insurance Business America. David is a trusted high net worth insurance expert who’s published more than 200 articles. His articles & press releases have generated over 500K pageviews and has been featured on blogs such as Google News, Yahoo Finance, CNBC, Market Watch, Fox, The New York Times, etc. David founded Coastal Insurance Solutions in 2001 after earning a BBA from the State University of New York College at Oswego.

IBA's Top Retail Broker 2023
Digital badge for the 2023 Insurance Agents of the Year Award, featuring intricate design elements that symbolize excellence and achievement in the insurance industry.
IBA's Top Retail Broker 2023
Digital badge for the 2023 Insurance Agents of the Year Award, featuring intricate design elements that symbolize excellence and achievement in the insurance industry.

Helpful Home Insurance Articles