Uncover the Best Homeowners Insurance Options in New York

/* Inline styles converted to CSS */
.metasync-inline-1 { border-collapse: collapse; }
.metasync-inline-2 { border: 1px solid rgb(193,193,193); padding: 6px; background-color: rgb(233,233,233); text-align: center; }
.metasync-inline-3 { border: 1px solid rgb(193,193,193); padding: 6px; background-color: rgb(233,233,233); text-align: center; }
.metasync-inline-4 { border: 1px solid rgb(193,193,193); padding: 6px; background-color: rgb(233,233,233); text-align: center; }
.metasync-inline-5 { border: 1px solid rgb(193,193,193); padding: 6px; background-color: rgb(233,233,233); text-align: center; }
.metasync-inline-6 { border: 1px solid rgb(193,193,193); padding: 6px; background-color: rgb(233,233,233); text-align: center; }
.metasync-inline-7 { border: 1px solid rgb(193,193,193); padding: 6px; background-color: rgb(233,233,233); text-align: center; }
.metasync-inline-8 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-9 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-10 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-11 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-12 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-13 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-14 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-15 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-16 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-17 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-18 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-19 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-20 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-21 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-22 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-23 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-24 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-25 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-26 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-27 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-28 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-29 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-30 { border: 1px solid rgb(193,193,193); padding: 6px; }
.metasync-inline-31 { border: 1px solid rgb(193,193,193); padding: 6px; }
v5 72173 regen d7ce7cad

Homeowners across the country face a wide range of premiums depending on location, carrier, and coverage level, with costs shifting significantly from state to state. Chubb ranks as a top-rated insurer for high-value homes nationwide. Coastal Insurance Solutions, an independent agency headquartered in Rocky Point, NY, serves homeowners across the majority of U.S. states, providing access to distinguished carriers including Chubb for tailored homeowners policies wherever a client lives.

Key Takeaways for Best Homeowners Insurance

  • Chubb ranks among the top-rated insurers for high-value homes nationwide.
  • Flood damage is excluded from standard home insurance policies in most states.
  • Average premiums vary significantly by state, carrier, and coverage level, so there is no single "lowest" number nationwide.
  • Shopping for homeowners insurance quotes saves homeowners meaningful money annually by surfacing options a single carrier never offers.

What makes a home insurance policy best? A Home Insurance Guide
v5 72173 regen 83b2f708

A best homeowners insurance policy addresses a property’s specific risk profile, which varies widely from coastal flood zones to wildfire regions to tornado alleys. Standard coverage falls short wherever flood exposure and high property values intersect. Homeowners across the country face storms, wildfires, and flooding, yet flood damage is not covered by standard home insurance in nearly any state. That gap leaves families exposed to catastrophic financial loss after a single weather event, regardless of where they live.

Home insurance guide principles start with carrier strength. Chubb is a top-rated insurer nationally, offering strong coverage for high-value homes. A policy from a financially secure carrier matters when claims surge after a regional disaster. Weaker insurers delay payouts or impose stricter terms precisely when homeowners need relief most.

What coverage gaps do homeowners overlook? Insights for Best Homeowners Insurance

Flood insurance remains the most dangerous blind spot almost everywhere. Standard policies exclude flood damage, including storm surge and overflowing waterways, in the vast majority of states. Homeowners who skip this protection risk losing their entire dwelling investment after one severe storm.

Sewer backup and water damage endorsements also prove critical, especially in older neighborhoods with aging infrastructure. A single heavy rainfall can overwhelm municipal systems and send contaminated water into finished basements, a risk that shows up in cities across the country, not just one region.

How do high-value homes change the insurance equation? Guidance from a Home Insurance Guide

Luxury properties demand replacement cost valuations that mass-market carriers rarely provide. High-value insurers like Chubb include extended replacement cost and cash-out settlement options. These features prevent underinsurance when construction costs spike after a disaster.

Coverage for fine art, jewelry, and collections also separates premium policies from standard ones. A homeowners insurance quotes comparison reveals that specialized carriers offer higher sublimits and fewer exclusions for valuable personal property. Homeowners who skip this analysis often discover coverage gaps only after filing a claim.

For homeowners unable to secure coverage on the regular market, most states maintain some form of FAIR plan or insurer of last resort, though the specific program, eligibility rules, and coverage limits vary considerably from state to state. In New York, that program is the New York Property Insurance Underwriting Association, which provides basic coverage when standard carriers decline a property. That variation is exactly where an experienced advisor provides the greatest value: Coastal Insurance Solutions helps clients across the country navigate these state-by-state differences, matching each home’s profile to the right carrier, whether a standard market policy or a residual market fallback.

How much does homeowners insurance cost? Advice for Comparing Homeowners Insurance Quotes
v5 72173 regen de9e8e64

Homeowners insurance costs vary sharply by state, carrier, and coverage level, and New York home insurance follows that pattern closely. Average premiums for a policy with $500,000 in dwelling coverage and $100,000 in liability coverage can differ by hundreds of dollars a year depending on location alone, before carrier and coverage choices even enter the picture. For New York properties, Long Island and coastal New York City homes typically carry higher premiums than inland upstate properties, reflecting hurricane and storm surge exposure along the shoreline. Premiums climb quickly for homes with higher rebuild values, coastal exposure, wildfire risk, or older construction, no matter which state a property sits in. A New York home insurance guide worth consulting accounts for these regional differences within the state itself, not just differences between states.

Rates have surged nationally in recent years. A 2025 Consumer Federation of America report found that home insurance premiums increased by an average of 24 percent over the prior three years. Homeowners who renew without comparing alternatives absorb that full increase. The Zebra reports that shopping for homeowners insurance quotes saves an average of $482 per year when comparing options from top providers. That savings gap widens for high-value properties where carrier pricing models diverge more dramatically, and it widens further still in states where the market is more fragmented.

What drives home insurance premiums higher? A Home Insurance Guide Perspective

Location is the dominant factor, and it works differently in every state: wind and flood risk along the coasts, wildfire exposure out West, hail and tornado risk through the plains. Standard carriers price each of these aggressively, and the “right” carrier for one state is rarely the right one for another. Replacement cost also matters everywhere. A home insurance guide from Coastal Insurance Solutions emphasizes that luxury homes with custom finishes, slate roofs, or historic details require specialized valuation regardless of location. Standard replacement cost estimators often undervalue these features. The resulting coverage gap leaves homeowners underinsured after a loss.

Which carriers offer the best homeowners insurance for high-value homes? Detailed Comparison Table Included

Carriers like Chubb, AIG Private Client Group, and PURE design policies specifically for properties exceeding $1 million in replacement value. These insurers include extended replacement cost, cash-out settlement options, and risk consulting services. Coastal Insurance Solutions provides access to these carriers alongside standard market options across the states it serves. Comparing quotes across both tiers reveals whether a high-value policy delivers better protection at a competitive price point.

CarrierAverage Annual PremiumDwelling CoverageExtended Replacement CostCash-Out SettlementSpecialized Coverage
Chubb$2,200Up to $5M+YesYesFine art, jewelry, collections
PURE$2,100Up to $3M+YesNoHigh-value personal property
Travelers$1,600Up to $1MNoNoStandard coverage
State Farm$1,550Up to $750KNoNoStrong local agent network

Which carriers offer the best coverage for homeowners? A Best Homeowners Insurance Review
v5 72173 regen 54e78386

Homeowners nationwide face a fragmented insurance market where carrier quality varies dramatically by property type and by state. NerdWallet’s 2026 analysis identifies five standout insurers, each serving a distinct segment of homeowners. Choosing the wrong carrier leaves high-value properties underinsured and standard homes overpaying for coverage gaps that only surface during a claim.

Chubb earns a top overall rating nationally, delivering the best homeowners insurance for high-value residences. The carrier specializes in luxury properties with replacement costs that exceed standard policy limits. Chubb policies include extended replacement cost coverage and cash settlement options that standard carriers do not offer. For owners of architecturally significant homes or properties with custom finishes, this coverage prevents catastrophic out-of-pocket rebuild costs.

Which insurer works best for most homeowners? Homeowners Insurance Quotes Explained

State Farm provides a strong option for the typical homeowner. The carrier balances competitive pricing with a broad agent network across the country. Policyholders gain access to local claims support and multi-policy discounts that reduce total premium burden.

What about military families and regional preferences? Guidance from a Home Insurance Guide

USAA stands as a top choice for military families nationwide. The carrier consistently scores high on claims satisfaction surveys. Membership eligibility extends to active-duty service members, veterans, and their immediate families.

Andover Companies operates as a leading regional insurer in the Northeast, offering coverage tailored to that region’s property risks, a reminder that strong regional carriers exist in nearly every part of the country. Amica secures a strong consumer experience rating nationally, reflecting superior customer service and claims handling. Each carrier addresses a specific homeowner profile, and matching that profile to the right insurer, in the right state, determines whether a claim resolves smoothly or becomes a financial setback.

How do I compare homeowners insurance quotes? A Practical Guide to Homeowners Insurance Quotes
v5 72173 regen 4499950e

Comparing homeowners insurance quotes requires evaluating premiums, coverage limits, and carrier financial strength side by side. For a New York property, gathering homeowners insurance quotes ny homeowners can actually rely on means accounting for the state’s flood zones, coastal exposure, and FAIR plan rules alongside the standard premium comparison. A disciplined comparison process prevents homeowners from leaving substantial savings unclaimed each year, wherever they live.

The Zebra reports that shoppers who compare multiple carriers save an average of $482 annually on their premiums. That figure represents real savings forfeited when a homeowner renews without surveying the market. Coastal Insurance Solutions streamlines this process by representing major homeowners’ insurance carriers writing policies across the country. The company’s advisors pull quotes from Progressive, Allstate, Liberty Mutual, and other top providers in a single consultation.

What details matter most when comparing quotes? Insights from a Home Insurance Guide

Dwelling coverage limits must reflect actual rebuild costs, not market value. Liability protection thresholds deserve equal scrutiny. A policy with a lower premium but inadequate coverage creates exposure that costs far more than the savings, a trap that catches homeowners in every state.

How many quotes should a homeowner gather? Recommendations for Best Homeowners Insurance

Three to five quotes establish a reliable baseline for the home insurance guide approach to comparison. Fewer than three quotes leaves pricing blind spots. Because carrier strength and pricing differ so much by state, Coastal Insurance Solutions eliminates the legwork by assembling multiple carrier options simultaneously, drawing on a nationwide panel so clients get proposals suited to their own state’s market rather than generic quotes.

Quote comparison also demands attention to deductibles, water damage exclusions, and windstorm provisions. These variables shift out-of-pocket costs dramatically. A disciplined review of each line item, not just the annual premium, identifies the best homeowners insurance fit for a specific property and risk profile.

Essential Buying Checklist: Get the Best Homeowners Insurance by Comparing Homeowners Insurance Quotes
v5 72173 regen e551b922

Actionable Steps to Secure the Best Coverage

  1. Assess the property's rebuild cost: Accurate estimates that reflect custom features and upgrades help avoid underinsurance.
  2. Gather 3 to 5 homeowners insurance quotes: Compare top carriers' pricing, coverage limits, and policy terms side-by-side.
  3. Evaluate carrier financial strength and claims reputation: Insurers with strong ratings provide prompt and fair claims handling.
  4. Confirm coverage inclusions and exclusions: Flood insurance requirements, sewer backup endorsements, and windstorm provisions each vary by state and warrant careful review.
  5. Review policy options for high-value items: Fine art, jewelry, and collections require adequate coverage with appropriate sublimits.
  6. Consider multi-policy discounts and bundling opportunities: These can lower overall premium costs.
  7. Work with an independent insurance broker: An independent broker provides access to a broader carrier panel and unbiased advice tailored to a specific state and property.
  8. Understand deductibles and out-of-pocket costs: Premium savings should be balanced against potential claim expenses.
  9. Verify eligibility for regional or specialized carriers: Such as USAA for military families or a strong regional insurer in a given part of the country.
  10. Update coverage annually: Reassessing values and market changes keeps protection aligned with a home's current worth and risks.

Following this checklist helps homeowners obtain the best homeowners insurance tailored to their needs, ensuring peace of mind and financial security no matter which state they call home.

What should I look for in a home insurance guide?
v5 72173 regen 6ae31ef5

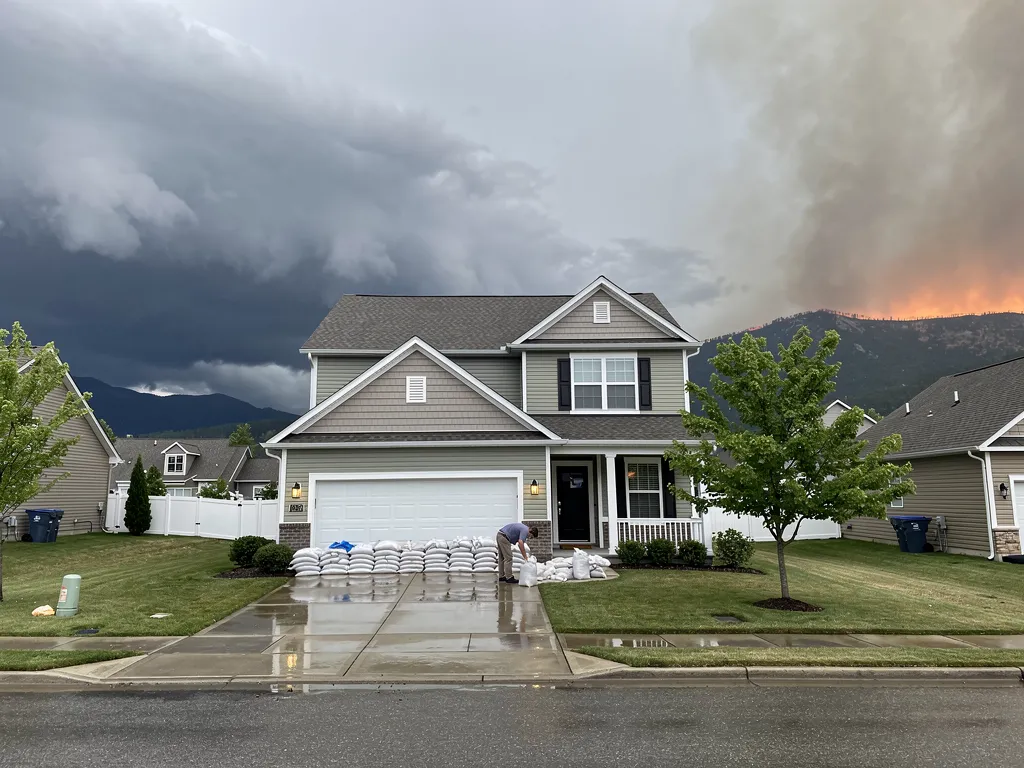
A reliable home insurance guide must address a property’s unique risk profile rather than apply a one-size-fits-all standard. Homeowners across the country face natural disasters such as storms, wildfires, and flooding, but flood damage is not covered by standard home insurance in nearly any state. This coverage gap leaves property owners exposed to catastrophic financial loss from hurricanes, wildfires, and coastal surge events alike, depending on where they live.

What flood coverage options exist for homeowners?

Standard homeowners policies exclude flood damage entirely in nearly every state, and New York is no exception. Property owners need a separate flood insurance policy, typically through the National Flood Insurance Program or a private carrier. The risk is not theoretical for New York homeowners: Hurricane Sandy flooded large portions of New York City, Long Island, and other parts of the state, and FEMA data shows more than 20 percent of NFIP flood claims come from areas never designated as high-risk flood zones in the first place. Coastal Insurance Solutions, a family-owned independent insurance agency rooted on Long Island since 2001 and now serving homeowners across the majority of U.S. states, helps clients compare flood coverage options against their property’s specific flood zone and elevation profile, wherever that property is located.

Luxury properties demand coverage limits and policy features that mass-market carriers rarely provide. A guide worth following explains the difference between replacement cost and extended replacement cost, and identifies carriers that specialize in high-value dwellings with custom construction and premium finishes.

A practical guide also maps out the path for homeowners who struggle to find coverage. If a property cannot qualify for home insurance on the regular market, every state maintains some version of a FAIR plan or insurer of last resort, though the name, rules, and coverage limits differ from state to state. This insurer of last resort provides basic protection when standard carriers decline the risk. Working with an independent agency streamlines this process. Coastal Insurance Solutions accesses both the admitted market and residual market options across the states it serves, matching each property to the most appropriate solution without leaving gaps in protection, and translating state-specific rules into a clear plan for the homeowner.

FAQ

What is the average cost of homeowners insurance?

Average premiums vary significantly by state, carrier, and coverage level, so homeowners should compare quotes for their specific property rather than rely on a single nationwide figure.

Which insurer is best for high-value homes?

Chubb ranks as a top-rated insurer for high-value homes nationwide, offering extended replacement cost and cash-out settlement options.

Does standard homeowners insurance cover flood damage?

Flood damage is excluded from standard home insurance policies in nearly every state, leaving homeowners exposed to catastrophic financial loss unless they carry a separate flood policy.

Conclusion

v5 72173 regen 4b182003

Selecting the right homeowners insurance requires matching a property’s profile to a carrier with the financial strength and coverage structure to support it, wherever in the country that property sits. Whether the priority is high-value protection, flood exposure, or a competitive premium, the decision rests on comparing dwelling limits, liability thresholds, and exclusions with discipline. Because pricing and rules shift from state to state, a thorough review of three to five quotes, guided by an independent advisor with a nationwide carrier panel, positions homeowners to secure coverage that performs when a claim matters most.

Need assistance now?

Give us a call:
(631) 782-3175

Homeowners Insurance Articles

About the Author

David W. Clausen is the CEO of Coastal Insurance Solutions. With over 20 years' experience and over 1 billion insured, David and Coastal Insurance Solutions are the recognized leaders in high net worth insurance. For the fifth consecutive year, David Clausen has been awarded Top Producer by Insurance Business America. David is a trusted high net worth insurance expert who’s published more than 200 articles. His articles & press releases have generated over 500K pageviews and has been featured on blogs such as Google News, Yahoo Finance, CNBC, Market Watch, Fox, The New York Times, etc. David founded Coastal Insurance Solutions in 2001 after earning a BBA from the State University of New York College at Oswego.

IBA's Top Retail Broker 2023
Digital badge for the 2023 Insurance Agents of the Year Award, featuring intricate design elements that symbolize excellence and achievement in the insurance industry.
IBA's Top Retail Broker 2023
Digital badge for the 2023 Insurance Agents of the Year Award, featuring intricate design elements that symbolize excellence and achievement in the insurance industry.

Helpful Home Insurance Articles